Choosing between a unit and a house is usually a trade-off between land, location, and cash flow. In Australia, the better option depends on their budget, borrowing power, target tenant, and how long they plan to hold the property.
Is buying a unit for investment better than a house? Sometimes, especially when location and affordability matter more than land, but it is not a universal rule.
Is buying a unit for investment better than a house in Australia right now?
Is buying a unit for investment better than a house? It can be when they want a lower entry price and stronger rental demand close to CBDs, universities, and hospitals. Units often let them buy into suburbs they could not afford if they insisted on a house.
A house can still win if they are targeting long-term land-driven growth and can handle higher upfront and ongoing costs. The best choice is usually the one that matches their strategy rather than the one that sounds safest.
What actually drives capital growth for units versus houses?
Houses tend to benefit from land scarcity, so growth is often stronger over long holds in established suburbs. Units can still grow well, but outcomes vary more by building quality, supply levels, and the suburb’s density pipeline.
In Australian markets, a well-located unit in a tightly held suburb can outperform a house in an oversupplied fringe estate. Growth is less about the label and more about the asset’s scarcity, appeal, and replacement risk.
How does land value change the investment maths?
Land is the part that usually appreciates most over time, which is why houses often look attractive on paper. With units, land value is shared via lot entitlement, so their exposure to land appreciation is diluted.
That does not automatically make units inferior. It just means they should be more selective and focus on small, low-rise blocks in established suburbs, where the land component per unit is typically higher than in high-rise towers.
Are units usually cheaper to buy and easier to finance?
Units are often cheaper, which can reduce deposit pressure and lender’s mortgage insurance, and may improve serviceability. That lower buy-in can help them start sooner or diversify across more than one property over time.
Finance can still get tricky for certain unit types. Some Australian lenders scrutinise very small apartments, high-density postcodes, student-only accommodation, or buildings with issues, so they should check lending policy before they sign anything.
Do units tend to have better rental yield than houses?
Units often show stronger rental yields in inner and middle-ring suburbs where rents are supported by lifestyle demand. That can help them manage holding costs, especially when rates are high or their household income is stretched.
Houses can have solid yields too, but the purchase price is often higher, which can compress yield. They should compare yield on a like-for-like suburb basis rather than using state-wide averages.
What ongoing costs should they expect for units compared to houses?
Units come with strata levies, which fund building insurance, common-area maintenance, and sinking funds. Those costs can be worth it, but they must be priced in from day one because levies can rise, particularly in older or poorly maintained buildings.
Houses avoid strata, but they carry their own costs like building insurance, roof repairs, fences, gardens, and driveways. The “no strata” advantage is real, but it does not mean “no costs.”
How big of a risk are strata problems in Australian unit blocks?
Strata risk is manageable when they do proper due diligence. The main issues tend to be low sinking funds, deferred maintenance, high insurance premiums, water ingress, or expensive cladding and defect rectification.
They should review the strata report, meeting minutes, capital works plan, and any litigation history. If the building has a pattern of special levies, constant disputes, or major works with no funding plan, they are effectively buying a future bill.
Do houses outperform units across all Australian cities?
No, performance varies widely by city and cycle. In some periods, houses in Sydney and Melbourne have pulled away due to land scarcity, while units can lag if there is heavy construction supply in certain corridors.
But the opposite can happen when affordability bites and buyers trade down into units. In those phases, well-located units can catch a strong tailwind as first-home buyers and investors compete for the same stock.
Does location matter more for units than houses?
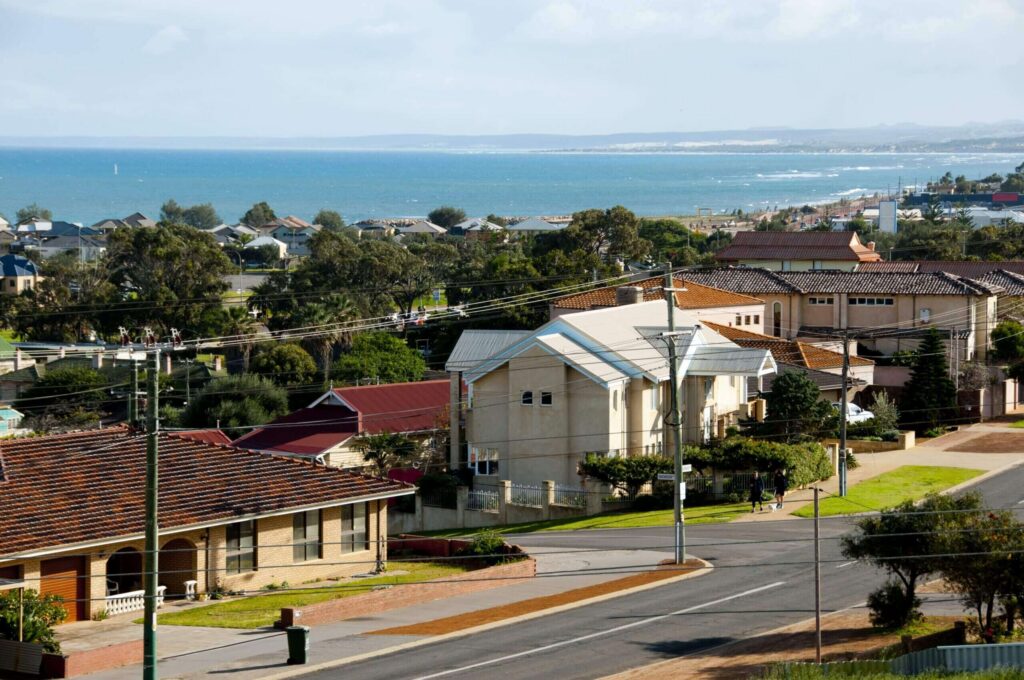
Yes, because units rely heavily on convenience and amenity to stay in demand. A unit near a train line, employment hub, university, beach precinct, or major hospital often rents faster and holds value better than a similar unit in a weak location.
Houses also benefit from location, but land can sometimes soften a mediocre address. With units, they should assume location is the growth engine, so compromises can cost them more.
How should they think about supply risk for units?
Supply risk is one of the biggest differences. A suburb can add hundreds of near-identical apartments quickly, which caps price growth and increases vacancy risk if demand slows.
They can reduce this risk by avoiding areas with constant high-rise approvals, focusing on boutique blocks, and choosing floorplans that are hard to replicate. In many Australian suburbs, older low-rise stock is naturally limited, which helps support scarcity.
Which option is usually better for cash flow and vacancy?
Units can be easier to keep tenanted in high-demand areas because renters prioritise commute time and lifestyle. That can mean fewer vacancy gaps and steadier cash flow, especially for one and two-bedroom apartments close to jobs.
Houses may have longer tenant stays when they attract families, but vacancy can be more painful if the rent is high and the tenant pool is smaller. The key is matching the property to the dominant renter demographic in that suburb.
What type of tenant do units and houses attract in Australia?
Units often attract singles, couples, students, and downsizers, particularly in inner and middle-ring areas of Brisbane, Sydney, Melbourne, Perth, and Adelaide. They value walkability, transport, and low maintenance.
Houses often attract families who want space, yards, and access to schools. That tenant profile can be stable, but the property must fit family expectations, including parking, storage, and liveable layouts.
How do maintenance and renovation prospects compare?
A house offers more control over renovations and value-add projects, such as extensions, landscaping, or adding a granny flat where permitted. That can help them manufacture equity if they are skilled and the suburb supports end values.
Units can still be improved with kitchens, bathrooms, flooring, and styling, but they cannot change the building envelope. Strata rules can also limit changes to windows, balconies, air-conditioning placement, and flooring acoustic standards.
What about tax and depreciation differences for Australian investors?
Both units and houses can offer depreciation benefits, depending on age and the assets inside. Newer properties typically provide more depreciation on fixtures and fittings, and sometimes on capital works, which can improve after-tax cash flow.
They should not buy purely for depreciation, because it is a secondary benefit and can reduce cost base for CGT. A qualified quantity surveyor report is usually the cleanest way to estimate benefits for an Australian investment property.
Is buying a unit for investment better than a house for first-time investors?
Is buying a unit for investment better than a house? It often is for first-time investors when affordability, risk management, and learning the ropes matter most. A cheaper unit can reduce stress and allow them to enter a stronger suburb sooner.
A house might still be right if they have a bigger deposit and want maximum land exposure. But for many, the first win is simply buying a good asset they can comfortably hold through rate changes and vacancies.
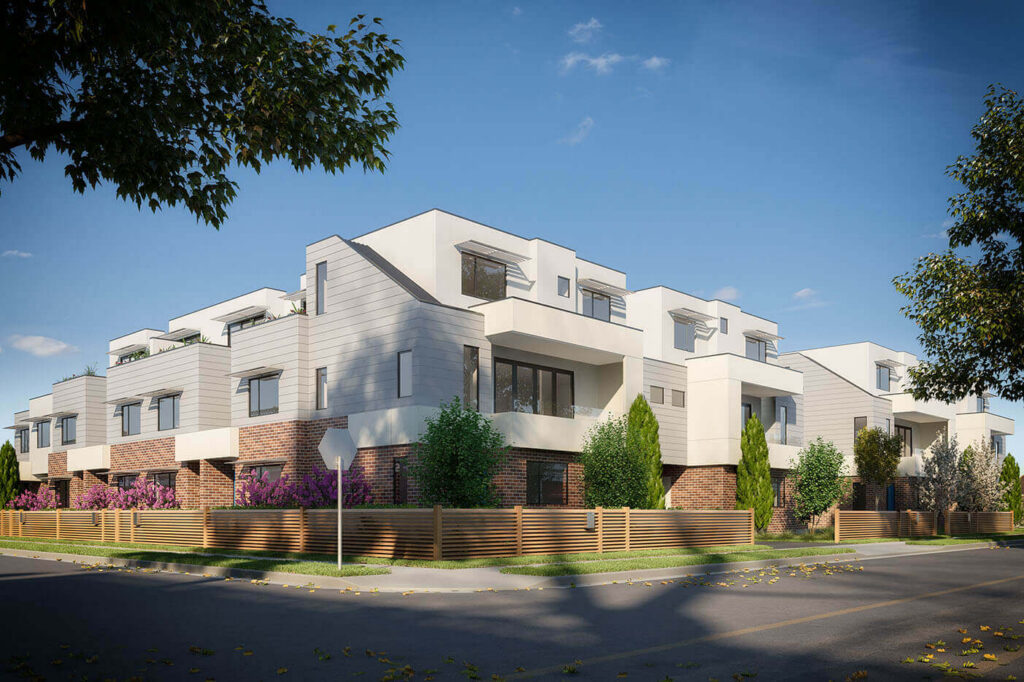
Is buying a unit for investment better than a house when interest rates are high?
Is buying a unit for investment better than a house? It can be, because the lower loan size may be easier to service and the yield can be higher in inner areas. That combination can reduce the chance they need to sell under pressure.
A house may still outperform over time, but only if they can comfortably fund the shortfall. In a high-rate environment, survivability matters, and cash flow buffers can be the difference between holding and folding.
Is buying a unit for investment better than a house for long-term wealth?
Is buying a unit for investment better than a house? It depends on whether they can buy a scarce unit in a premium location versus a house in a compromised one. Over the long term, quality and scarcity are usually stronger drivers than property type.
Many Australians build wealth with either asset, but the consistent winners tend to avoid oversupply, choose locations with enduring demand, and keep the property long enough for compounding to work.
What due diligence should they do before buying a unit?
They should treat the building like a business they are buying into. That means reading the strata report, checking sinking fund health, confirming insurance, and reviewing recent and upcoming works.
They should also inspect common areas, look for signs of water issues, and understand owner-occupier versus investor mix. A building with high owner-occupier appeal often holds up better in softer markets.
What due diligence should they do before buying a house?
They should check the basics, including building condition, drainage, termite risk, and any unapproved structures. In many Australian councils, planning overlays, flooding, bushfire zones, and heritage controls can affect future renovations and resale appeal.
They should also confirm comparable sales and realistic rent. Paying a premium for a “dream house” feeling is easy, but investment performance is usually driven by numbers and buyer demand.
How can they decide between a unit and a house in their target suburb?
They should compare two or three options in the same suburb, not different postcodes. The goal is to measure what they get for the money: transport access, tenant demand, vacancy rates, comparable rents, and future supply.
Is buying a unit for investment better than a house? The answer is usually found in this suburb-by-suburb comparison, because Australian markets are local and the best deal is often the one with the strongest scarcity and easiest holding costs.
What is a practical decision checklist they can use?
They should choose a unit when the priority is buying well-located stock they can afford, with strong rental demand and manageable holding costs. They should choose a house when they can buy in a strong location and still comfortably carry the loan, while gaining meaningful land exposure.
Is buying a unit for investment better than a house? It is when the unit is scarce, well-located, and financially sustainable for them to hold. If the only affordable house option forces them into a weaker area, a quality unit can be the smarter Australian investment.
FAQs (Frequently Asked Questions)
Is buying a unit for investment better than a house in Australia?
Buying a unit can be better when prioritizing lower entry price and strong rental demand near CBDs, universities, and hospitals. Units allow access to suburbs unaffordable for houses. However, houses may be preferable for long-term land-driven growth despite higher costs. The best choice depends on your investment strategy rather than a universal rule.
What drives capital growth differences between units and houses?
Houses benefit from land scarcity leading to stronger growth over long holds in established suburbs. Units’ growth varies based on building quality, supply levels, and suburb density. A well-located unit in a tightly held suburb can outperform a house in oversupplied fringe areas. Growth depends more on asset scarcity, appeal, and replacement risk than property type.
How does land value impact investment returns for units versus houses?
Land typically appreciates most over time, making houses attractive on paper. Units share land value via lot entitlement, diluting exposure to appreciation. This means units require selective investment focusing on small, low-rise blocks in established suburbs where the land component per unit is higher than high-rise towers.
Are units generally cheaper to buy and easier to finance than houses?
Units often have lower purchase prices reducing deposit pressure and mortgage insurance, improving borrowing capacity. This lower buy-in helps start investing sooner or diversify across properties. However, some lenders scrutinize certain unit types like very small apartments or buildings with issues; checking lending policies before purchase is essential.
Do units offer better rental yields compared to houses?
Units frequently show stronger rental yields in inner and middle-ring suburbs due to lifestyle-driven rent demand, aiding holding cost management especially when interest rates are high. Houses can have solid yields but higher purchase prices may compress yield. Comparing yields within the same suburb provides more accurate insights than state-wide averages.
What ongoing costs should investors expect when choosing units versus houses?
Units incur strata levies covering building insurance, common-area maintenance, and sinking funds; these levies can rise especially in older buildings and must be factored into costs from the start. Houses avoid strata fees but have expenses like building insurance, roof repairs, garden upkeep, fences, and driveways. Both property types carry ongoing maintenance costs that impact cash flow.
Other article: Are Refinance Cashback Offers Actually Worth the Switching Costs?

Leave a Reply